& meet dozens of singles today!
User blogs
The growth of remote working and managing workforces that are distributed well beyond the confines of a centralized physical office — or even a single country — have put a spotlight on the human resources technology that organizations use to help manage those people. Today, one of the HR startups that’s been seeing a surge of growth is announcing a round of funding to double down on its business.
Oyster, a startup and platform that helps companies through the process of hiring, onboarding and then providing contractors and full-time employees in the area of “knowledge work” with HR services like payroll, benefits and salary management, has closed a Series A round of $20 million.
The company is already working in 100 countries, and CEO and Tony Jamous (who co-founded the company with Jack Mardack) said in an interview that the plan is to expand that list of markets, and also bring in new services, particularly to address the opportunity in emerging markets to hire more people. In terms of services, currently Oyster does not cover candidate sourcing or any of the interviewing and evaluation process: those could be areas to build or partner to provide them as part of its one-stop shop.
“There 1.5 billion knowledge workers coming into the workforce in next 10 years, mostly from emerging economies, while in developed economies there are some 90 million jobs unfilled,” Jamous said. “There are super powers you can gain from being globally distributed, but it poses a major challenge around HR and payroll.”
Emergence Capital, the B2B VC that has backed the likes of Zoom, Salesforce, Bill.com and our former sister site Crunchbase, is leading the funding. The Slack Fund (Slack’s strategic investment vehicle), and London firm Connect Ventures (which has previously backed the company at seed stage) are also participating. The investment will accelerate Oyster’s rapid growth, and support its mission of enabling people to work from anywhere.
Oyster’s valuation is not being disclosed. The startup has raised about $24 million to date.
One of the great ironies of the global health pandemic is that while our worlds have become much smaller — travel and even local activities have been drastically curtailed and many of us spend day in, day out at home — the employment opportunity and scope of how organizations are expected to operate has become significantly bigger.
Public health-enforced remote working has led to companies de-coupling workers from offices, and that has opened the door to seeking out and working with the best talent, regardless of location.
This predicament may have become more acute in the last year, but it’s been one that has been gradually coming into focus for years, helped by trends in cloud computing and globalization. Jamous said that the idea for Oyster came to him was something that he’s been thinking about for years, but became more apparent when he was still at his previous startup, Nexmo — the cloud communications provider that was acquired by Vonage for $230 million in in 2016.
At Nexmo we wanted to be a great local employer, headquartered in two countries but wanted to have people everywhere,” he said. “We spent millions building employment infrastructure to do that, becoming knowledgable about local laws in France, Korea and more countries.” He realised quickly that this was a highly inefficient way to work. “We weren’t ready for the complexity and diversity of issues that would come up.”
After he moved on from Nexmo and did some angel investing (he backs other distributed work juggernauts like Hopin, among others), he decided that he would try to tackle the workforce challenge as the focus of his next venture. That was in mid-2019, pre-pandemic. It turned out that the timing was spot on, with every organization looking in the next year at ways to address their own distributed workforce challenges.
The emerging market focus, meanwhile, also has a direct link to Jamous himself: he left his home country of Lebanon to study in France when he was 17, and has essentially lived abroad since then. But as with many people who move into developed from emerging markets, he realised that the base of technical talent in his home country was something that was worth tapping, using tech to help.
Related to its wider social mission, Oyster has a pending application to become a B-Corporation.
Jamous is not the only one that founded an HR company based on his personal experience: Turing’s founders have cited their own experience growing up in India and working with people remotely from there, while Remote’s founder hails from Europe but built Gitlab (where he had been head of product) based on a similar premise of tapping into the talent he knew existed all around the world.
And indeed, Oyster is not alone in tackling this opportunity. The list of HR startups looking to be the ADP’s of the world of distributed work include Deel, Remote, Hibob, Papaya Global, Personio, Factorial, Lattice, Turing and Rippling. And these are just some of the HR startups that have raised money in the last year; there are many, many more.
The attraction of Oyster seems to come in the simplicity of how the services are provided — you have options for contractors, and full-timers, and full, larger staff deployments in other countries. You have options to add on benefits for employees if you choose. And you have some tools to work out how hires fit into your bigger budgets, and also to guide you on remuneration in each local market. Pricing starts at $29 per person, per month for contractors, to $399 for working with full employees, to other packages for larger deployments.
“It has a few well funded competitors, but that’s usually a good signal,” said Jason Green, the Emergence partner who led on its investment. “But you want to bet on the horse that will lead the race, and that comes down to execution. Here, we are betting on a team that’s done it before, an entrepreneur experienced in building a company and selling it. Tony’s made money and knows how to build a business. But more than that, he’s mission driven and that will matter in the space, and to employees.”
If you were itching to launch an email newsletter via Twitter, following its acquisition of the Dutch newsletter platform Revue last month, it appears you’ll have to wait a little bit longer for the official unveiling — although some Twitter users are reporting being able to sign up for the newsletter publishing tool right now.
The social media company confirmed to TechCrunch it’s reverted Revue’s Publisher offer back to private beta for the moment — saying this means it’s only accessible to existing customers at this time.
Nonetheless, it also appears to have quietly flipped the launch switch over the last 12 hours or so — at least for some users.
Earlier today, a number of TechCrunch staffers were able to go through the process of setting up a Twitter Revue newsletter — including our very own Editor-in-Chief, Matthew Panzarino.
setting up my twtrevue pic.twitter.com/VTAZPFSCTY
— Matthew Panzarino (@panzer) February 1, 2021
At the time of writing India-based reporter, Manish Singh, also has access to the interface — which prompts Twitter users to set up a free newsletter to reach their audience, flagging features such as the ability to embed tweets, import email lists, analyze engagement and earn money from subscribers.
So it looks as if Twitter has been testing a newsletter launch in a number of markets. It’s less clear whether/if it aborted a planned launch. We’ve asked the company for more details and will update this post with any response.
Unless you’ve been on a very long digital detox you’ll have noticed that newsletters have been having quite the moment of late. The rise of platforms that help writers monetize their content via an email-delivery format presents a clear risk/opportunity to Twitter, a company that relies on an army of users freely and publicly contributing short-form content.
But with Twitter launching its own in-house newsletter, tweets can potentially inflate in value — becoming the top of the funnel for Twitter users to build a community of followers who they made be able to convert to paying subscribers for longer form content, delivered in a newsletter format.
Twitter told us today that it has put new sign-ups to Revue on ice so it can focus on improving the offering in order to effectively meet the demand of new customers — and make Revue an even more powerful tool for publishers.
It added that it’s working quickly to roll out a new version that’s open to new customers, with a spokeswoman pointing to a mailing list for interested parties to sign up to get the latest updates here.
It’s not clear exactly why Twitter might have aborted a launch — or whether it was just quietly testing sign-ups in select markets, which at least three of our writers happened to be able to access. As we reported last month, it had already been working to integrate the newsletter into its platform and is clearly moving at a clip to get Revue plugged in so it can start to capitalize on the hype and momentum around paid newsletters.
Simultaneously, preventing users from finding a home for their longer form thoughts elsewhere is also likely front of mind for Twitter — as competition for attention in the social sphere heats up, such as from the likes of (rival) newsletter platform Substack (which has been building momentum since 2017); and buzzy live-voice chat app Clubhouse (which has recently captivated the clique-loving technorati).
But it seems Twitter feels its Revue newsletters aren’t quite ready for the prime time just yet.
For those eager to know more about how ‘Twitter + Revue’ will work in practice, here’s the lowdown from our very own @refsrc — who does have early access.
The newsletter feature, available from the three-dot “More” menu option on Twitter’s web interface, enables a user to sign up for Revue with a few clicks using their social account. Once onboard, users can begin drafting their newsletter and drag their recent tweets to it — if they so choose.
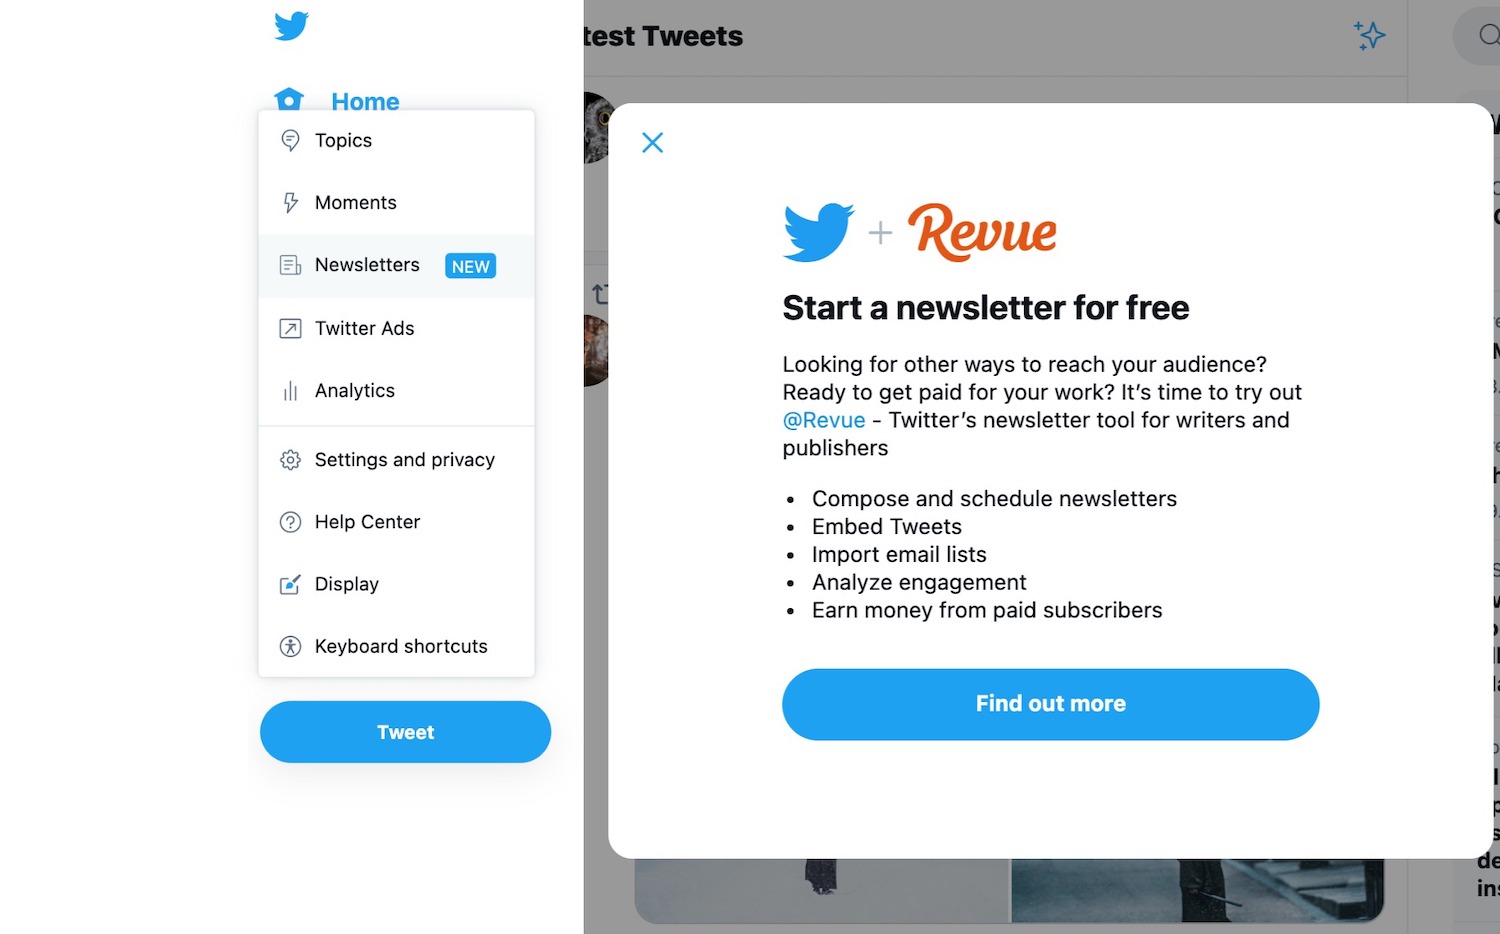
Image credit: TechCrunch
The newsletter platform, which competes with among others Andreessen Horowitz-backed Substack, maintains integration support for a number of third-party services including Facebook, Instagram, Pocket, Product Hunt, Instapaper, and even RSS feeds. Once users have integrated these services, they can drag and drop stories from those feeds to the newsletter.
In the current avatar, users can manually add email addresses of subscribers, or import a list from Mailchimp or a CSV file. On the welcome screen, which noted reverse engineer Jane Manchun Wong first spotted last week, Twitter also advertises that its newsletter can help writers and publishers earn money from paid subscribers.
Like before, Revue lets users schedule their newsletters. All in all, there doesn’t appear to be any additional features in this entire workflow.
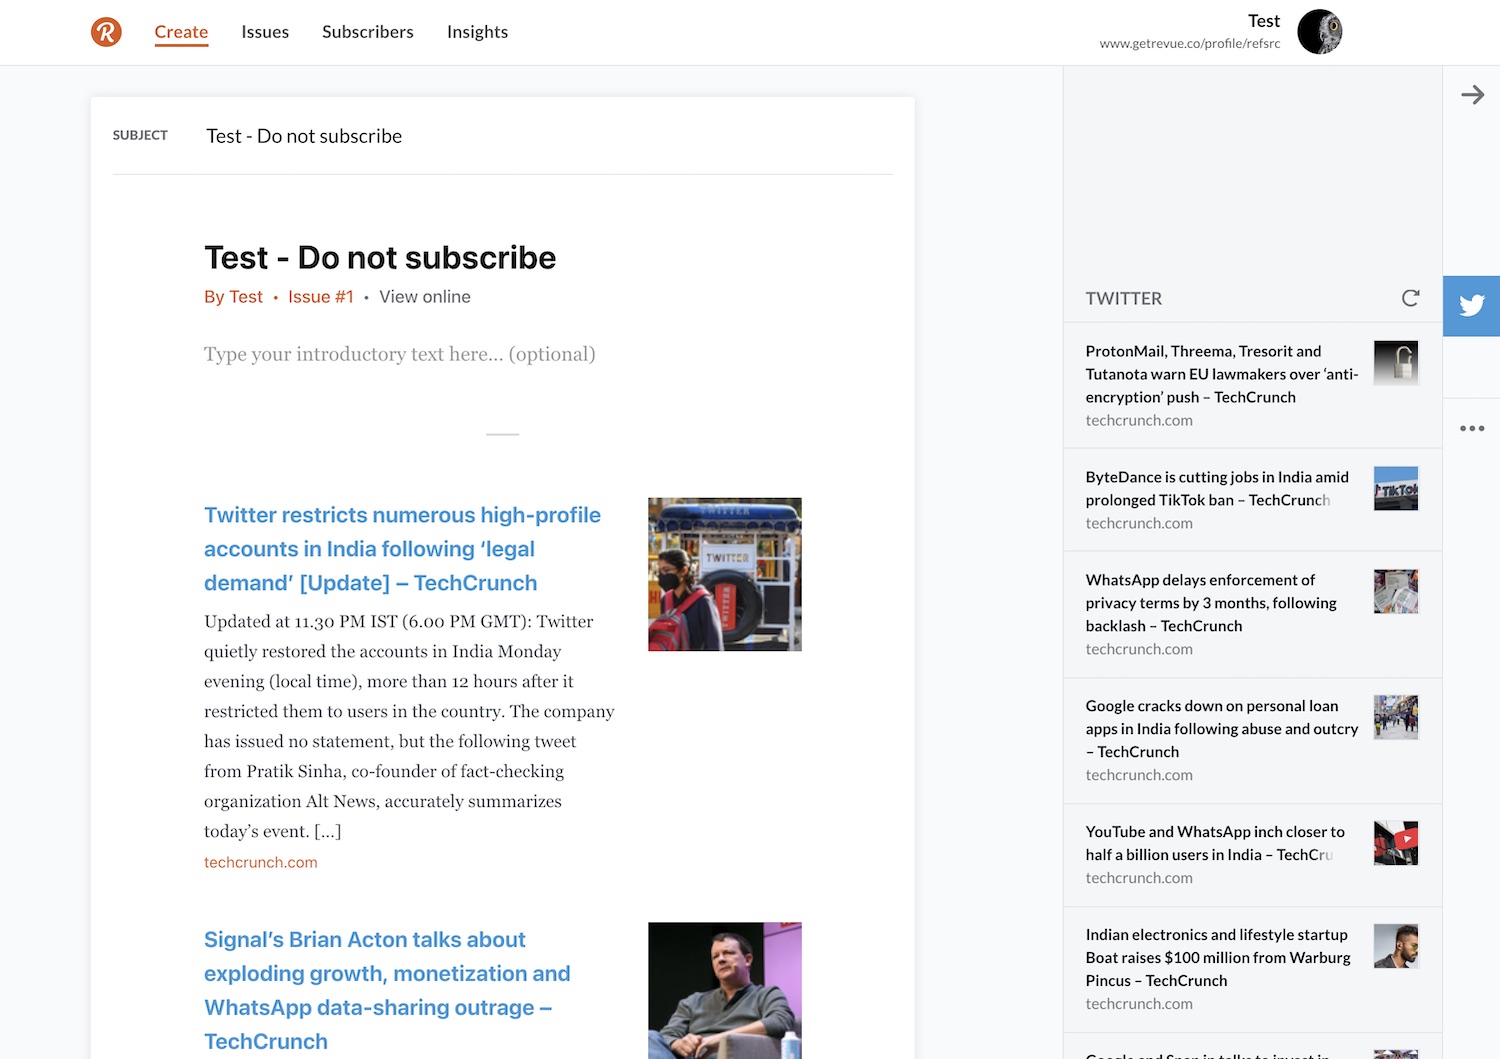
Image credit: TechCrunch
Source: https://techcrunch.com/2021/02/02/twitter-quietly-rolls-out-revue-newsletters-integration-on-web/
French startup Seyna is getting a new CEO. Stephen Leguillon is joining the company as chief executive while Philippe Mangematin is stepping back from day-to-day activities for personal reasons — he’ll become honorary chairman.
If you’re not familiar with the company, Seyna is an insurtech startup that has obtained an insurance license focused on property and casualty. This is a significant move as the French regulator (ACPR) hasn’t handed out a new license in this category since 1983.
The company’s go-to-market strategy is also interesting as it doesn’t sell insurance products to consumers directly. Instead, the company is building out insurance-as-a-service products. It partners with other companies that offer Seyna’s insurance products under their own brands.
Behind the scenes, Seyna offers an API to generate insurance contracts on demand — an API is a programming interface that lets two services interact with each other. You can also connect directly to Seyna’s interface to manage contracts.
Seyna has created its own core insurance system, which is an important differentiating factor compared to legacy players. The startup can generate many different variants that cover around 20 different insurance products — pet insurance, ticket cancelation, rent guarantee, etc. Clients include Garantme and Decathlon.
The company’s new CEO Stephen Leguillon previous co-founded La Belle Assiette, a company that lets you hire a chef for a dinner at home and that I covered on TechCrunch. He added a second product called GoCater, a corporate catering service — GoCater was letter spun out from La Belle Assiette and acquired by ezCater.
Seyna has raised a €14 million seed round ($17 million at today’s rate) from Global Founders Capital, Allianz France, Financière Saint James and several business angels. Insurance companies require a ton of capital to operate, that’s why the seed round seems quite big for the French market.
Prakhar Singh and ex-Paystack employee Abdul Hassan have known each other for seven years, building different tech products individually and collectively along the way.
Before joining Paystack in 2018, Hassan co-founded OyaPay, a payments startup the year before. After leaving the Stripe-owned company in 2019, he launched a data startup called Voyance where Singh, who had already exited one of his products — Transferpay.ng, an offline payments startup — was a software engineer.
Last June, the duo started working on Mono, a project that would allow companies to access their customers’ financial accounts in Nigeria.
By streamlining various data in a single API, companies and third-party developers can retrieve vital information like account statements, real-time balance, historical transactions, income, expense and account owner identification. Of course, this isn’t without users’ consent as they are required to login with their internet or mobile login credentials before any transaction takes place.
Following a series of tests and iterations, Mono launched its beta version in August, with Hassan as CEO and Singh as CTO. A month later, the startup closed a $500,000 pre-seed investment from early-stage investors like Lateral Capital, Ventures Platform, Golden Palm Investments and Rally Cap. It was one of the notable pre-seed rounds on the continent because of the length of time it took from launch to funding, a trait other API fintech startups in the region share, albeit with significantly longer timelines.
In a region where more than half of the population is either unbanked or underbanked, these open finance players are trying to improve financial inclusion on the continent. Open finance thrives on the notion that with access to a financial ecosystem via open APIs and new routes to move money, access financial information and make borrowing decisions, the barriers and costs of entry for the unbanked and underbanked might come down.
However, for Hassan, Mono’s play overlaps open finance and open banking. Although the two terminologies portray what these African startups want to accomplish, the CEO believes that they are subject to regulation from the government and apex financial institutions. Mono is a data company playing in the fintech space, he says.
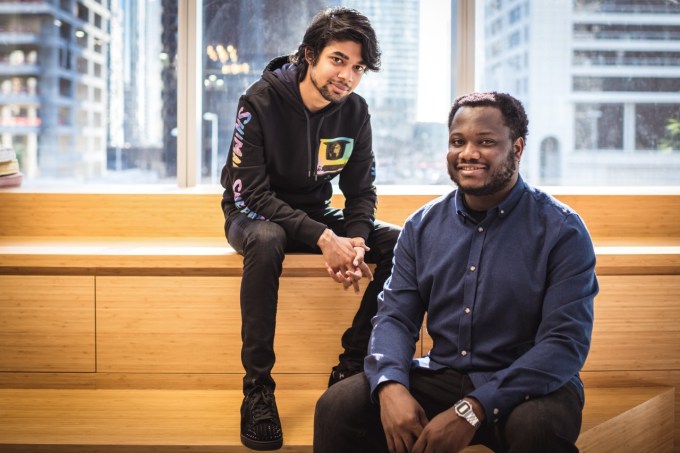
Prakhar Singh (CTO) and Abdul Hassan (CEO)
He likened Mono to how Google was in its early days when it started with a simple mission to organize the world’s information and make it accessible. Decades later, Google has metamorphosed into an internet giant playing in a plethora of sectors.
“If you ask me, I’ll say we don’t see ourselves entirely in open banking or finance,” he told TechCrunch. “Today, we’re concerned about how we can get data from different sources and aggregate into a database where businesses can get access to them with our users’ consent. Down the line, we can use this data for different use cases and solve various problems.”
Mono has already secured partnerships with more than 16 financial institutions in Nigeria and has a little over a hundred businesses like Carbon, Renmoney, Flutterwave and Indicina using its platform. They process about 5 million datasets per hour, the CEO claims.
These clients are mainly lending companies with a few others in proptech and health tech, which allow users to pay for their services in installments. But there are plans to diversify this clientele. One such way will be to improve onboarding processes on applications through its one-click signup feature.
From a user’s perspective, here’s how it works when considering two savings applications: Users submit their KYC to the first savings app. But for one reason or the other, maybe due to a better interest rate, some users switch to a second savings app.
However, there’s a little hassle in that a second KYC is needed for this process. What Mono has done with the one-click signup feature is to let users transfer their data from the first app to the second without repeating the process. And to that end, Mono has partnered with two of Nigeria’s leading savings and investment platforms to roll out the service.
“First, we’ve enabled companies with a new infrastructure that allows them to get access to customers’ financial accounts and understand their history before giving them loans or any financial service. Now, we think with the new generation of companies coming up in Africa, Mono will be the one to power their onboarding processes,” Hassan remarks on the platform’s offerings.
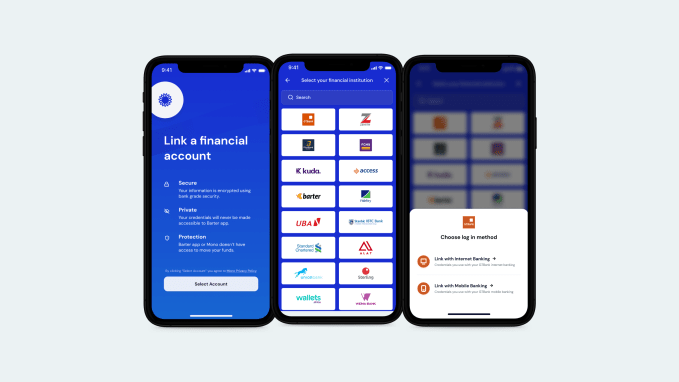
Image Credits: Mono
For any investor, Mono’s sticky features, coupled with explosive growth, looks too good of an opportunity to pass on. Today, the six-month-old startup announced that it has been accepted into Y Combinator’s Winter 2021 batch. It will receive $125,000 in seed funding with an opportunity to receive follow-up investment after graduating in March. The startup also joins 39 other African startups per YC data which have passed through the accelerator since 2009.
Getting into the accelerator helps Mono with one of its biggest challenges. According to Hassan, Mono has come across users who are still skeptical to input their internet banking details on the platform due to personal experiences with online fraud in the country.
“To date, we’ve been focusing on building, and I think we’ve gotten to a stage where we’re seeing some people not wanting to use their internet banking on Mono.” But with YC’s backing and a conscious offline marketing plan afterwards, the founder thinks Mono’s credibility can get a lift.
At Paystack, where Hassan was a product manager, he was privileged to experience firsthand the company’s innovation and growth before it was acquired by Stripe last year. He says he learned the ropes of product development and management, and hiring — lessons that have stuck with him to Mono, a company now with 13 staff across Nigeria and India.
The plan for Mono is to be a global company and getting into YC provides the perfect opportunity to do so. The company is also planning an imminent pan-African expansion to Ghana and Kenya, and from all indication, Mono might execute one if not the two before the end of Q1. Setting the company up for expansion and the hiring spree that comes with it will require capital, so a seed round is in the works to facilitate the whole process.
Digital ordering and paying at restaurants was already gaining much ground in China before the COVID-19 pandemic hit. The tap-to-order method on a smartphone is part of the greater development in China where cash and physical documentation is increasingly being phased out. Many restaurants across large cities go as far as making digital menus mandatory, cutting staff costs.
Meanwhile, there has been pushback from the public and the authorities over aggressive digitization. An article published this week by People’s Daily, an official paper of the Chinese Communist Party, was titled: “Scan-to-order shouldn’t be the only option.”
Aside from harming consumers’ freedom of choice and removing the human interaction that diners might appreciate, mandatory smartphone use also raises concerns over data privacy. Ordering on a phone often requires access to a person’s profile on WeChat, Alipay, Meituan or other internet platforms enabling restaurants’ digital services. With that trove of data, businesses will go on to span users with ads.
“These approaches harm consumers’ data protection rights,” the People’s Daily quotes a senior personnel at the consumer rights unit of China Law Society, China’s official organization of legal academic professionals, as saying.
China has similarly targeted the ubiquity of cashless payments. In 2018, China’s central bank called rejecting cash as a form of payment “illegal” and “unfair” to those not accustomed to electronic payments, such as senior citizens.
The elderly also face a dilemma as digital health codes, which are normally generated by tracking people’s movement history using location data from SIM cards, becomes a norm amid the pandemic. Without a smartphone-enabled health pass, senior citizens could be turned away by bus drivers, subway station guards, restaurant staff and gatekeepers at other public venues.
To bridge the digital divide, the southern province of Guangdong recently began allowing citizens to check their health status by tapping their physical ID cards on designated scanners.
Cashless payment is an irreversible trend though. Between 2015 and 2020, the digital payments penetration rate amongst China’s mobile internet users went from less than 60% to over 85%, according to official data. Moreover, the government is hastening the pace to roll out digital yuan, which, unlike third-party payments methods, is issued and managed by the central bank and serves as the statutory, digital version of China’s physical currency.
Source: https://techcrunch.com/2021/02/01/china-criticize-contactless-payments/


